Editor: Porcia Akua Holmes
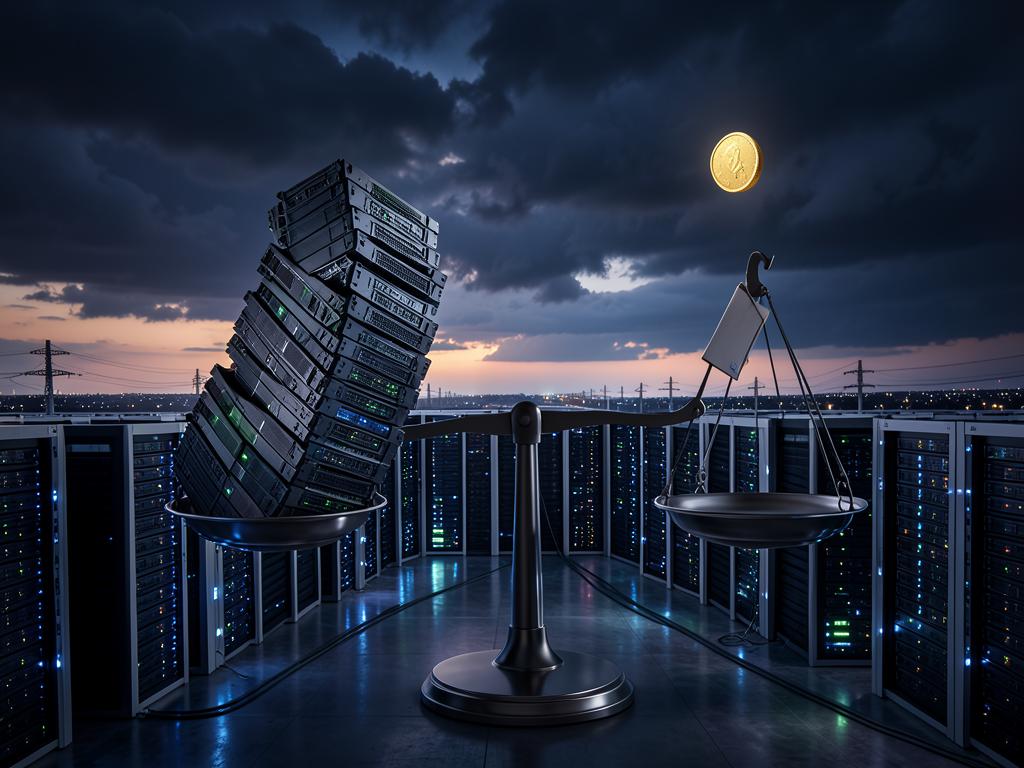
The artificial intelligence buildout is moving at breakneck speed, but the economics behind it are growing less certain. A fresh wave of industry analysis suggests data centre investments have reached a level where AI would need to generate roughly $6 trillion in annual revenue to justify the spending. That figure dwarfs the entire software industry today, and it has investors, tech executives and energy providers rethinking their exposure.
The Scale of the Gap
Data centre construction has surged over the past two years, fueled by the race to train and deploy large language models. Hyperscale operators like Microsoft, Google and Amazon have committed billions to new facilities, while Nvidia's GPU sales have broken records. Yet the revenue side has not kept pace. Consumer subscriptions for AI tools remain modest, and enterprise adoption, while growing, has not produced the explosive returns that would justify current capex levels.
The $6 trillion figure is not a single forecast but a consensus point from multiple financial models. It represents the annual revenue needed to deliver a reasonable return on the cumulative invested capital by the end of the decade. To put that number in perspective, the entire global software market generated about $650 billion in 2024. AI would need to multiply that by nearly ten times in less than six years, an outcome that even the most optimistic analysts call a stretch.
Several forces are pushing costs higher with no matching revenue lift:
Who Bears the Risk
The exposure is not limited to a single company. Nvidia depends on continued cloud demand for its chips. Microsoft and Google have made AI a central pillar of their cloud growth. Startups like OpenAI have raised enormous capital on the promise of future monetisation, but they remain loss-making. Even utility companies and grid operators are now betting on a permanent surge in electricity consumption, a bet that pressures them to build new plants on spec.
Investors have already shown signs of impatience. Public markets have rewarded AI-related stocks for two years, but any sign that revenue growth is slowing could trigger a sharp repricing. Private investors, meanwhile, continue to pour money into AI startups at valuations that assume near-perfect execution.
Why This Matters
The stakes extend beyond share prices. If the current buildout fails to generate the expected return, the fallout would chill future investment in energy infrastructure, high-end chips and research. That would slow the pace of AI adoption across healthcare, logistics and education, exactly the sectors that stand to benefit most from cost declines in intelligence.
A correction, however, is not inevitable. The $6 trillion target could be reached if AI moves beyond chatbots into autonomous systems, deep scientific discovery and large-scale automation. The difference hinges on whether enterprises find ways to turn AI into durable profits, not just productivity experiments. The next 18 months will likely reveal whether the revenue line can catch up to the capital line, or whether the industry must pause its most expensive ambitions.
What Could Change the Math
Two developments could narrow the gap. First, a substantial drop in inference costs would make AI affordable for a much wider set of business functions, expanding the addressable market. Second, the emergence of truly profitable AI-native products, such as autonomous agents that replace entire workflows, could create the high-margin revenue streams that current models lack. Neither development is guaranteed, but both are plausible within the same period that data centre investments are slated to ramp up.