Editor: Porcia Akua Holmes
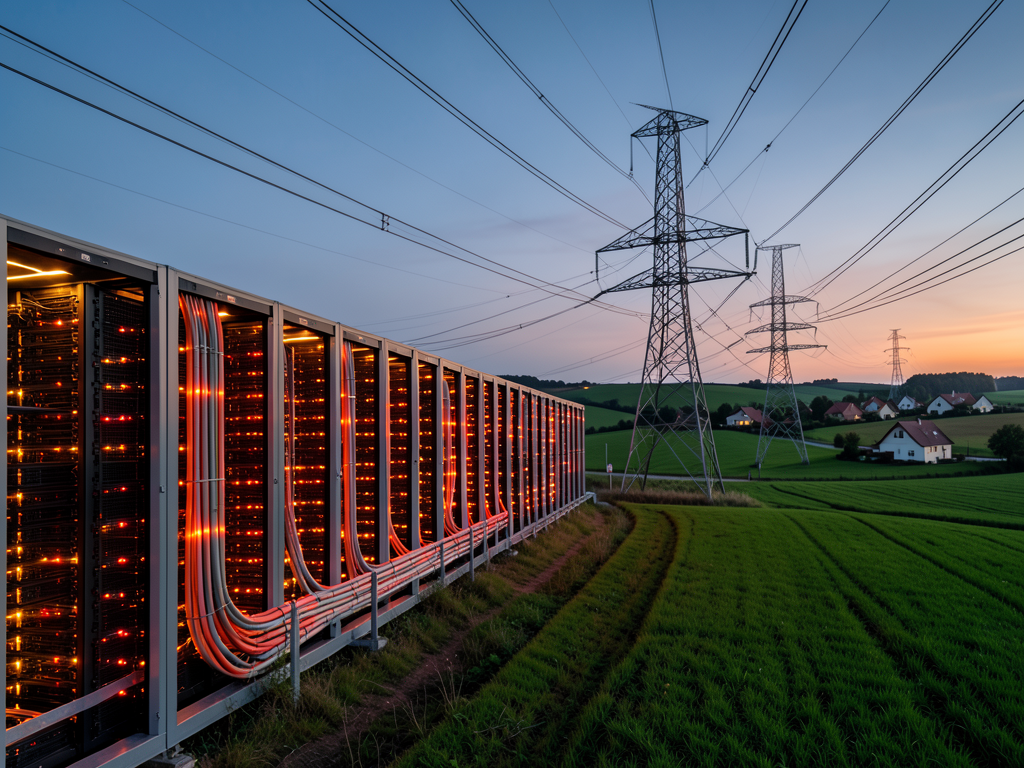
Europe's rapid data center expansion is colliding with an uncomfortable reality: the electricity grid cannot absorb the surge without someone paying for it. A new analysis from Moody's warns that the continent's push to host more computing capacity could translate directly into higher power bills for ordinary households and businesses.
Why This Matters
The financial burden of Europe's digital infrastructure buildout is quietly shifting toward consumers. Grid operators are being forced to reinforce transmission networks to handle concentrated loads from hyperscale facilities, and those costs are typically recovered through regulated tariffs applied to all ratepayers. This creates a structural mismatch: data center operators negotiate favorable connection terms while the public absorbs the systemic costs of network upgrades.
Utility companies face a dual-edged scenario. Rising demand could boost revenue and fund new generation capacity, but only if regulators allow cost recovery mechanisms that do not trigger political backlash. In Ireland, where data centers already consume 30% of national electricity, the margin for further expansion without significant price disruption is narrowing fast. The Nordics face a similar trajectory at 17% projected consumption.
What You Need to Know About the Grid Cost Shift
The mechanics of who pays for grid upgrades sit at the center of this debate. Data center developers typically cover the cost of connecting their facilities to the nearest transmission point. The wider reinforcement of the grid, however, falls under the regulated asset base of transmission operators, which is recovered through consumer tariffs.
The Policy Response Taking Shape
Moody's anticipates that European governments will face mounting pressure to intervene before electricity price increases become politically untenable. The playbook being discussed includes targeted tax relief for low-income households, temporary price caps during peak demand periods and stricter rules governing how data centers connect to national grids.
These measures mirror early steps taken in the United States, where the Trump administration introduced the Ratepayer Protection Pledge to shield consumers from data center-driven cost increases. Whether European nations adopt similar frameworks remains an open question, but the direction of travel is becoming clearer.
The utility sector, however, sees opportunity alongside risk. Additional revenue from data center contracts could fund investment in renewable generation and expanded transmission capacity. That outcome would require regulators to allow higher returns on infrastructure spending, a politically sensitive proposition in markets where energy affordability is already a flashpoint.
What Comes Next for European Energy Markets
The trajectory is set. Europe's data center capacity will continue to grow, driven by demand for cloud services, artificial intelligence workloads and digital sovereignty initiatives. The question is not whether electricity consumption rises, but who absorbs the cost of making the grid capable of delivering it.
Without coordinated policy intervention, the most likely outcome is a slow, uneven increase in consumer electricity bills across the continent. Ireland and the Nordic countries will feel it first. France and the UK will follow as their data center footprints expand. The window for proactive regulation is narrowing, and the decisions made in the next two to three years will determine whether Europe's digital ambitions come at an acceptable social cost.